← All news

Duck & Dry

Duck & Dry Outlines UK Expansion Plans Targeting 60 Franchise Sites

By UK Franchise Opportunities Editorial TeamPublished Updated
Duck & Dry Outlines UK Expansion Plans Targeting 60 Franchise Sites — UK franchise news

Blow-dry and beauty brand Duck & Dry has announced plans to expand its UK footprint, aiming to establish up to 60 franchised locations across major cities nationwide.

Duck & Dry, a specialist beauty business known for its premium blow-dry bars, has announced nationwide expansion plans aimed at establishing up to 60 franchise branches across the United Kingdom. The brand plans to introduce its experience-led salon concept into major urban centres throughout the country, marking a transition from a regionally concentrated footprint to a broad national network.

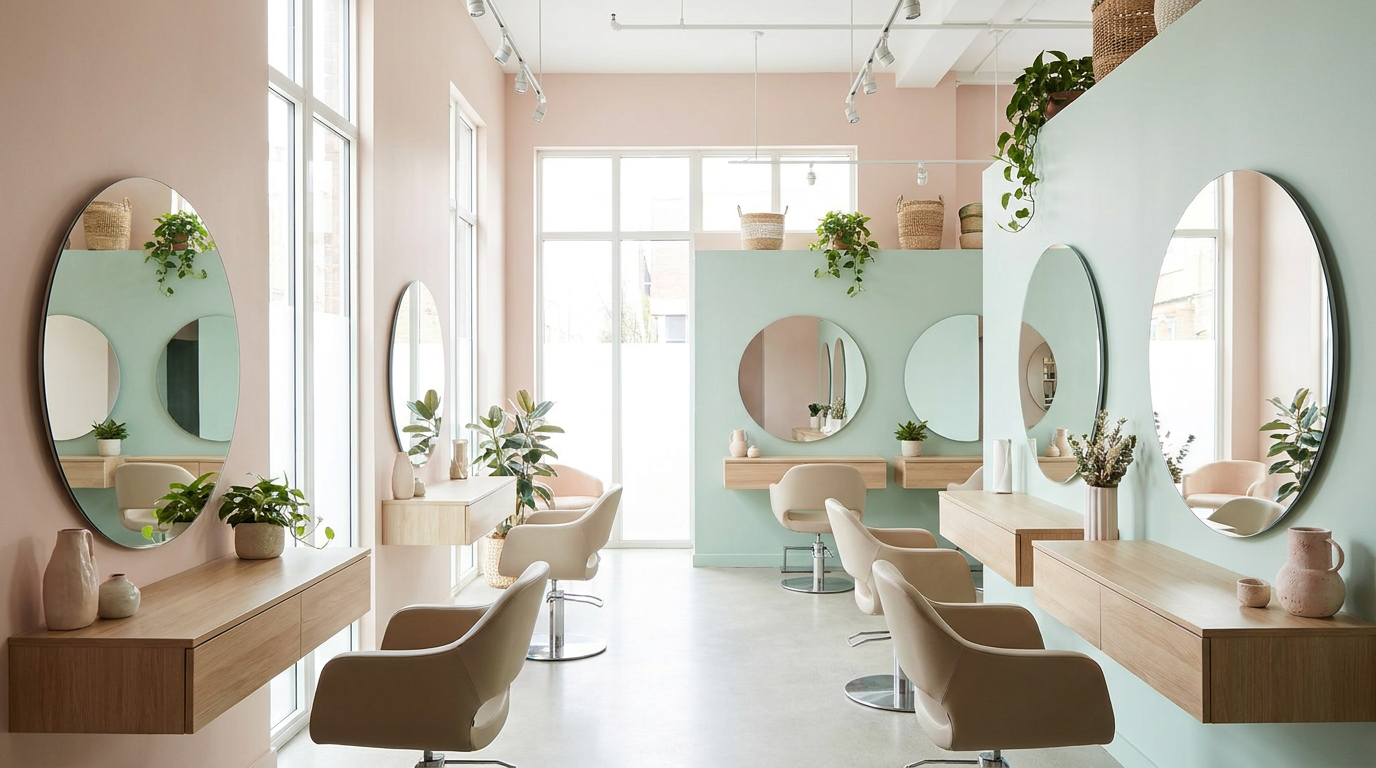
The company operates within the salon and personal care market, focusing specifically on dedicated styling and blow-dry services combined with an elevated customer experience. Under the franchise rollout, new operators will be sought to open and run branded locations across prominent high-street, shopping centre, and mixed-use commercial destinations in primary UK cities.

While the business has set out its target of 60 operational premises, comprehensive details regarding the exact opening schedule, target regional phases, and individual territory boundaries have not yet been formally released. The move places Duck & Dry among a growing contingent of consumer services turning to third-party franchising to scale physical presence rapidly without funding the full capital expenditure of corporate-owned sites.

Market Dynamics in Experience-Led Personal Care Franchising

The planned rollout highlights broader shifts within the UK personal grooming and salon industry. Traditional high-street hairdressing models frequently rely on full-service cutting and chemical colouring treatments, which demand broad technical capabilities and substantial service times per client. In contrast, specialised blow-dry bars concentrate on faster, styling-focused treatments that can drive higher customer throughput per styling station.

Positioning a salon around an experiential concept reflects wider commercial property trends across British town and city centres. As non-experiential retail increasingly moves online, landlords and asset managers have redirected leasing strategies towards personal care, leisure, and hospitality businesses that require in-person attendance. Specialised grooming brands benefit from this dynamic by securing prominent commercial space, provided the local demographic supports regular discretionary spending on personal maintenance.

Furthermore, standardising a service offering to blow-dries and styling allows a franchise network to simplify inventory requirements, staff training, and operational workflows. However, this focused service model also ties performance closely to consumer confidence, office occupancy levels, social calendars, and corporate event frequency within urban centres, all of which dictate weekday footfall and pre-weekend appointment spikes.

Practical Context and Due Diligence for Franchise Buyers

Investing in a high-street beauty or styling franchise involves distinctive capital commitments and operational responsibilities that prospective franchisees must evaluate carefully. The initial investment typically extends beyond the upfront franchise fee to encompass extensive premises fit-out, specialist plumbing and electrical installations, salon furniture, ventilation systems, point-of-sale software, and initial product inventory.

When reviewing a franchise prospectus or information pack for a personal care business, prospective investors should look closely at how financial projections are constructed. Candidate operators should request historical performance data from existing trading units rather than relying on theoretical capacity models. Important areas to assess include:

  • Occupancy and Chair Utilisation Rates: Models that assume near-capacity booking schedules throughout the working week often fail to reflect slower morning and midweek trading patterns. Investors must establish what baseline utilisation rate is required to break even after property rent, service charges, utilities, and commercial rates are settled.
  • Staffing Costs and Stylist Retention: Personal service businesses are labour-intensive. Prospective buyers need to examine typical staff turnover rates, commission structures, training costs, and whether the model relies on directly employed stylists or self-employed chair-rental agreements, alongside the associated tax and legal implications.
  • Product Margins and Supply Chain Mandates: Franchisors typically require franchisees to purchase branded products, retail lines, and styling consumables exclusively from approved suppliers. The financial review should clarify whether the franchisor applies a mark-up on supplies and whether retail sales margins generate meaningful net profit.
  • Territory Exclusivity and Local Marketing: Franchisees should verify the precise territorial protections afforded to their proposed location, ensuring clear boundaries that prevent competing company-owned or franchised branches from encroaching on their target catchment area.

Prospective franchisees should also consult professional advisers accredited by the Quality Franchise Association (QFA) to review franchise agreements and commercial leases before signing legally binding documents. Lease negotiations warrant rigorous examination, particularly regarding dilapidation liabilities, personal guarantees, rent-free fit-out periods, and break clauses.

Implications for Franchisors and Established Networks

A target of 60 locations represents a substantial scaling programme that places distinct demands on the central franchise operation. As a network expands from a modest footprint into dozens of regional locations, franchisors must transition from direct founder oversight to structured corporate governance and field-support systems. Failure to expand headquarters infrastructure concurrently with franchisee onboarding can result in degraded customer service standards and strained operational relationships.

For existing franchisees and the wider personal care sector, this scale of expansion illustrates several critical commercial considerations:

  • Supply Chain Scalability: Central warehousing and distribution arrangements must be sufficiently robust to supply dozens of regional sites with branded goods and styling products without delivery delays or stock shortages.
  • Consistency of Brand Standards: In experiential concepts, customer perception depends heavily on service ambiance, stylist presentation, and front-of-house interactions. Auditing mechanisms, mystery shopping programmes, and continuous training are necessary to safeguard network-wide reputation.
  • National Marketing Impact: As geographical coverage reaches critical mass, collective marketing levies can be redirected towards high-impact national media, consumer PR campaigns, and digital acquisition channels that benefit every operator across the network.
  • Multi-Unit Ownership Potential: Reaching a large footprint often depends on attracting multi-unit franchisees who possess the capital and managerial capability to develop several metropolitan territories simultaneously, reducing franchisor recruitment overheads.

What to Watch Next

Key developments to monitor will be the publication of specific target territories, confirmed franchise fees, and initial fit-out cost schedules by Duck & Dry. Prospective candidates, commercial landlords, and industry observers will also be watching the pace of initial franchise recruitment, the profile of incoming operators, and the geographic distribution of the first wave of regional openings beyond the brand's established operating base.

Reported from publicly available coverage. Details were correct at the time of writing.